 how-to
Courier Insurance for Valuable Items: A How-To Guide
Table of Contents
- What Courier Insurance Coverage Actually Protects
- Goods in Transit Insurance Requirements You Need to Know
- How to Package High-Value Items for Courier Delivery
- Declared Value vs. Carrier Liability: What's the Difference?
- Claims Process for Lost or Damaged Parcels
- Third-Party vs. Carrier-Provided Insurance: Which Offers Better Protection?
- Common Exclusions and Restrictions to Watch For
- Frequently Asked Questions
Last Updated: September 23, 2026
What Courier Insurance Coverage Actually Protects
Courier insurance valuable items coverage protects your shipments against financial loss if goods are damaged, lost, or stolen during transit. But here's what most people misunderstand: standard courier liability doesn't cover the full replacement cost of high-value items. That's where declared value and specialised goods in transit insurance come in.
When you ship something valuable, you're relying on a chain of people and systems, the courier driver, the sorting facility, the vehicle itself. Any weak link can result in loss. Insurance bridges that gap by guaranteeing compensation if something goes wrong.
The key distinction is between carrier liability (what the courier is legally obligated to pay) and insurance coverage (what you actually recover). Carrier liability limits are often capped at a fraction of your item's true value. A declared value declaration lets you tell the courier what your shipment is worth. Insurance, on the other hand, covers you directly regardless of what the carrier will pay.
At Direct Couriers London Ltd, we understand this distinction matters. Our fully insured fleet ensures your items are protected.
Goods in Transit Insurance Requirements You Need to Know
Courier insurance valuable items requirements vary depending on the value of your shipment and the courier service you choose. Most couriers offer basic coverage automatically, but this often caps compensation at a low threshold, sometimes as little as £20 per kilogramme.
For high-value items, you need to understand what "goods in transit" actually means. It's coverage that applies while your item is being transported, stored briefly at depots, or in the courier's care. The moment it's delivered and accepted by the recipient, the coverage typically ends.
Several requirements typically apply:
- Proof of value: The courier may ask for a receipt, invoice, or valuation certificate for items over a certain threshold
- Accurate description: You must describe the item accurately on the shipping label and in any insurance declaration
- Proper packaging: Items must be packaged to a reasonable standard, couriers can deny claims if packaging is obviously inadequate
- Timely claims: Most couriers require claims to be filed within a specific window, often 30 days after delivery
The insurance requirement that catches most people off guard is the need for documentation.
How to Package High-Value Items for Courier Delivery
Packaging standards for fragile and valuable goods aren't just best practice, they're often a requirement for insurance coverage to apply. A poorly packaged item gives the courier grounds to deny a claim, even if the damage was their fault.
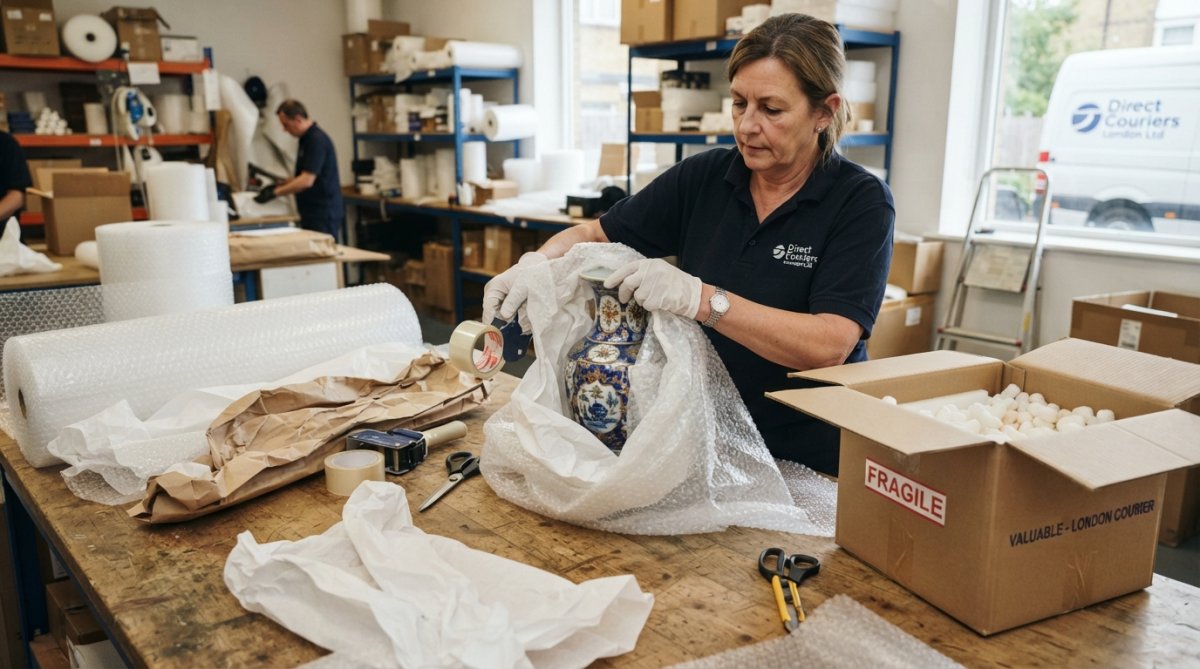
For antiques, furniture, or electronics, consider these specifics:
- Antiques: Wrap separately from the box using acid-free tissue first, then bubble wrap. Never let wood or fabric touch cardboard directly
- Electronics: Keep original packaging if possible. If not, use foam corners and wrap the device in anti-static bubble wrap
- Artwork: Use wooden crating for high-value pieces. Cardboard alone isn't adequate for items worth over £500
Packaging standards for fragile and valuable goods
Courier companies publish minimum packaging standards, and insurance providers reference them. Meeting these standards isn't optional if you want coverage, it's the baseline. Most require:
- Corrugated cardboard boxes rated for the item's weight
- Minimum 5 centimetres of cushioning material on all sides
- Sealed boxes with reinforced tape on all seams
- Weight and dimensions clearly marked on the box
Documentation and proof of value
This is where most claims fail. You need to prove three things: what you shipped, what it was worth, and that it arrived damaged or not at all.
Gather documentation before shipping:
- Original receipt or invoice showing purchase price
- Photographs of the item from multiple angles
- For antiques or collectibles, a professional valuation certificate
- Photographs of the packaging before sealing
- Tracking confirmation from the courier
Declared Value vs. Carrier Liability: What's the Difference?
Declared value and carrier liability are often confused, but they work very differently. Understanding this distinction can mean the difference between full compensation and a partial payout.
Here's the practical difference:
| Scenario | Standard Carrier Liability | With Declared Value |
|---|---|---|
| Item value: £1,500 | Compensation capped at ~£200 | Full £1,500 covered (minus excess) |
| Item value: £500 | Compensation capped at ~£100 | Full £500 covered (minus excess) |
| Item value: £3,000 | Compensation capped at ~£200 | Full £3,000 covered (minus excess) |
Claims Process for Lost or Damaged Parcels
When something goes wrong, the claims process is your only recourse. Understanding the steps and what evidence you'll need makes the difference between a quick resolution and a rejected claim.
Step-by-step claim filing
The claims process typically follows this sequence:
- Report immediately: Contact the courier within 24 hours of discovering damage or non-delivery. Delays weaken your claim
- Document the damage: Take clear photographs of the damaged item and packaging. If the item didn't arrive, photograph the empty packaging
- Complete the claim form: The courier will provide a formal claims form. Fill it out accurately with all requested details
- Submit supporting evidence: Attach receipts, photographs, valuation certificates, and proof of declared value
- Wait for assessment: The courier investigates, typically taking 5-10 working days
- Receive decision: The courier either approves and pays the claim, or denies it with reasons
- Appeal if rejected: If denied, you can escalate to the courier's complaints team or pursue the matter through alternative dispute resolution
The timeline matters. Most couriers have strict deadlines, often 30 days from delivery, for filing claims. Missing this window can result in automatic denial.
Evidence and documentation needed
This is where preparation pays off. The courier will ask for proof of everything: the item's value, its condition before shipping, and what happened to it.
Required documentation typically includes:
-
Proof of value: Original receipt, invoice, or professional valuation
-
Photographs: Before shipping (showing condition), after damage (showing extent of damage)
-
Packaging photographs: Before sealing, showing it met standards
-
Tracking information: Delivery confirmation and tracking history
-
Communication records: Any messages with the courier about the shipment
-
Repair or replacement quotes: If damaged, quotes for repair or replacement cost
-
Certificates of authenticity for collectibles
-
Professional condition assessments
-
Expert valuations for antiques or artwork
Third-Party vs. Carrier-Provided Insurance: Which Offers Better Protection?
You have two main insurance routes: using the courier's built-in coverage or purchasing separate third-party insurance. Each has trade-offs worth understanding.
The key differences:
| Factor | Carrier-Provided | Third-Party |
|---|---|---|
| Excess (your cost per claim) | Often £50-£150 | Often £25-£75 |
| Compensation limit | Capped at declared value | Often higher, negotiable |
| Claims process | Courier investigates | Independent assessor |
| Flexibility | Limited options | Customisable coverage |
| Cost | Included or small fee | Separate premium |
Common Exclusions and Restrictions to Watch For
Insurance policies always have exclusions, things they won't cover. Understanding these before you ship prevents nasty surprises when you file a claim.
Common exclusions across most courier insurance policies:
- Inadequate packaging: If the item wasn't packaged to standard, claims are often denied
- Undeclared value: If you didn't declare the true value upfront, compensation is capped at your declaration
- Prohibited items: Certain items (cash, jewellery, artwork over certain values) may require specialist coverage
- Wear and tear: Normal deterioration during transit isn't covered; only sudden damage is
- Consequential loss: If a delayed delivery costs you money (lost sale, missed deadline), that's not covered
- Items left unattended: If the package is left in an insecure location and goes missing, coverage may not apply
- Weather damage: Some policies exclude damage from rain, flooding, or extreme temperature unless the packaging failed
Restrictions also apply. Many policies require:
- Claims filed within 30 days of delivery
- Original packaging retained for inspection
- Photographic evidence of damage
- Professional valuations for items over a certain threshold
Frequently Asked Questions
What does courier insurance coverage for valuable items actually cover?
Courier insurance for valuable items covers loss or damage to goods in transit from collection to delivery. Standard cover typically includes accidental damage, theft, and loss, but exclusions apply to certain high-risk categories. Coverage limits depend on declared value and your policy terms. Third-party goods-in-transit insurance often provides broader protection than carrier liability alone, which may cap compensation at a fixed indemnity limit per kilogramme. Always verify specific exclusions with your courier before shipping.
How do I declare the value of high-value goods for courier insurance?
Declare the replacement cost of items, not their sentimental or resale value. Provide proof of value through purchase receipts, invoices, or valuation certificates, especially for antiques or bespoke items. Supply accurate descriptions and photographs. Some couriers require a signed valuation certificate for items exceeding a threshold (often £500-£1000). Underestimating value will result in proportionate compensation on claims. Document everything in writing and keep copies for your records.
What packaging standards must I follow for insurance claims to be valid?
Insurers expect industry-standard packaging appropriate to the item's fragility and value. Fragile items need cushioning materials (bubble wrap, foam corners, or air pillows), rigid outer boxes, and void fill to prevent movement. High-value goods may require specialist packaging or crating. Use multiple layers of protection and clearly mark packages as fragile. Inadequate packaging is a common reason claims are rejected, so document your packing process with photographs. Your courier can advise on specific standards for your items.
What is the difference between carrier liability and specialist goods-in-transit insurance?
Carrier liability is built into your courier's service and typically caps compensation at a fixed limit per kilogramme (often £20 per kg). Specialist goods-in-transit insurance offers higher coverage limits based on declared value and provides broader protection. Carrier liability may exclude certain items or circumstances; specialist insurance is tailored to your needs. For high-value shipments, third-party insurance is usually essential because carrier liability alone often falls short of replacement cost. Compare both options before deciding.